• Menu
  • Skip to right header navigation
  • Skip to main content
  • Skip to footer

Before Header

440.974.0808

  • Facebook
  • LinkedIn
  • Twitter
  • YouTube

Carver Financial Services

Helping you achieve your personal vision based upon your individual needs, goals and risk tolerance..

  • Our Approach
    • Personal Vision Planning®
    • Wealth Management Services
    • Team Advantage
  • About Us
    • Meet the Team
    • Our History
    • Awards & Recognition
    • Randy’s Story
    • Philanthropy
    • About Raymond James
  • Resources
    • Our Videos
    • Randy’s Blog
    • Raymond James Resources
    • Carver University
    • Resources for Business Owners
    • Client Access Videos
    • Client Communications
    • Seminar Material
    • Carver Financial ROKU® Channel
    • Carver in the News
    • FAQs
    • Carver Merch Store
  • Experiences
    • Our Events
    • Client Getaways
  • Contact Us
  • Client Login

Paige Courtot

Randy Carver Ranked #14 in the Nation on Barron’s Top 100 Independent Advisors List for 2026

September 21, 2026 //  by Paige Courtot

MENTOR, OH — September 18, 2026 — Carver Financial Services is proud to announce that Randy Carver, President and Founder of Carver Financial Services, has been ranked #14 in the nation on Barron’s 2026 Top 100 Independent Advisors list.

The recognition marks another significant milestone in Carver’s long history of recognition by Barron’s and reflects his continued commitment to serving individuals, families and organizations through comprehensive wealth management and financial planning.

“Being recognized by Barron’s among the nation’s leading independent advisors is an honor and a reflection of the dedication of our entire team,” said Randy Carver. “Our focus has always been on helping our clients navigate an increasingly complex financial world with thoughtful planning, personalized advice and a long-term perspective. This recognition belongs to the entire Carver Financial Services team and, most importantly, to the clients who place their trust in us.”

Barron’s Top 100 Independent Advisors ranking evaluates independent financial advisors using a combination of quantitative and qualitative factors. According to Carver Financial Services’ award disclosures, factors considered in Barron’s advisor rankings include assets under management, revenue, regulatory record, quality of practice, client-related factors, professional experience and philanthropic work. Investment performance is not an explicit component of the ranking.

Carver has been recognized by Barron’s for many years, including appearances on the publication’s Top 100 Independent Advisors list dating back to 2010. He was ranked #17 nationally on the 2025 Top 100 Independent Advisors list.

Carver Financial Services provides comprehensive wealth management and financial planning services designed to help clients pursue their financial goals and manage the complexities that accompany significant wealth.

About Randy Carver and Carver Financial Services

Randy Carver is the Founder and President of Carver Financial Services, an independent wealth management firm based in Mentor, Ohio. For decades, Carver and his team have provided comprehensive financial planning and wealth management services to individuals, families, corporations and institutions.

2026 Barron’s Top 100 Independent Advisors
Barron’s is a registered trademark of Dow Jones & Company, L.P. All rights reserved. The rankings as of 9/11/2026 are based on data provided by 728 applications and include qualitative and quantitative criteria. Time period upon which the rating is based is from 6/30/2025 to 6/30/2026, and was released on 9/11/2026. Data points that relate to quality of practice include professionals with a minimum of 7 years financial services experience, acceptable compliance records (no criminal U4 issues), client retention reports, charitable and philanthropic work, quality of practice, designations held, offering services beyond investments offered including estates and trusts, and more. Advisors are quantitatively rated based on varying types of revenues produced and assets under management by the financial professional, with weightings associated for each. Investment performance is not an explicit component because not all advisors have audited results and because performance figures often are influenced more by clients’ risk tolerance than by an advisor’s investment picking abilities. This ranking is not based in any way on the individual’s abilities in regards to providing investment advice or management. The ranking may not be representative of any one client’s experience, is not an endorsement, and is not indicative of an advisor’s future performance. Neither Raymond James nor any of its Financial Advisors pay a fee in exchange for this award/rating. Compensation provided for using the rating. Barron’s is not affiliated with Raymond James.

To view the full Barron’s Top 100 Independent Advisors list for 2026, visit www.barrons.com.

For more information about Randy Carver and Carver Financial Services, please visit www.carverfinancialservices.com or contact us at (440) 974-0808.
 

Category: Awards

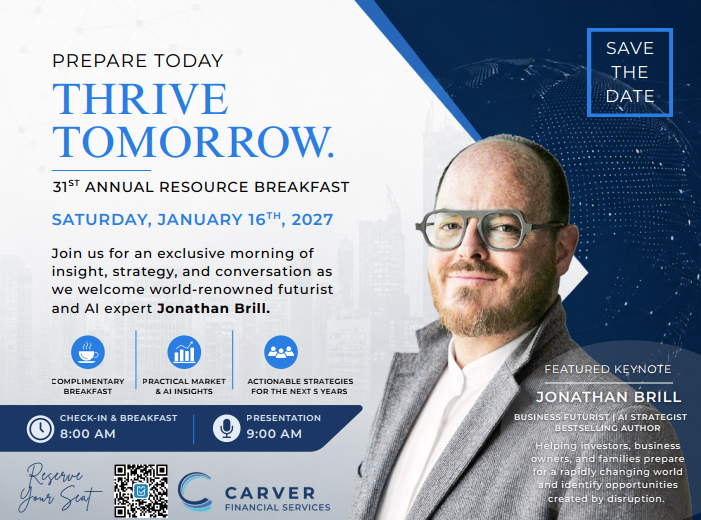
1.16.27 – 31th Annual Resource Breakfast

September 2, 2026 //  by Paige Courtot


31st Annual Resource Breakfast

Prepare today. Thrive tomorrow | An exclusive morning of insight, strategy, and conversation with world-renowned futurist and AI expert Jonathan Brill — built for investors, business owners, and families navigating a rapidly changing world.

Why attend:
A morning built around three things:

  1. Complimentary breakfast — Arrive at 8:00 AM to a full breakfast and time to connect with other attendees before the program starts.
  2. Practical market & AI insights — A clear-eyed look at where markets, technology, and disruption are heading, and what it means for your plan.
  3. Actionable strategies for the next 5 years — Leave with specific steps to prepare your investments, business, and family for what’s ahead.

Featured Keynote: Jonathan Brill | Business futurist · AI strategist · Bestselling author

Jonathan helps investors, business owners, and families prepare for a rapidly changing world and identify the opportunities created by disruption. Expect a candid, practical session — not a lecture on hype, but a working guide to what’s next.

Schedule:

  • 8:00 AM — Check-in & breakfast: Doors open. Enjoy a complimentary breakfast and time to connect before the program begins.
  • 9:00 AM — Keynote presentation: Jonathan Brill shares market insight, AI strategy, and what to prepare for over the next five years.
  • 10:00 AM — Q&A & closing: Open floor for questions, followed by closing remarks from the Carver Financial Services team.

When:

Saturday, January 16, 2027

8:00 – 9:00 AM Registration & Breakfast | 9:00 – 10:00 AM Presentation

Where:

Mentor Fine Arts Center | 6477 Center St | Mentor, OH 44060

You can register for this free event here.

This event will be recorded for your convenience. 

There is neither a cost nor any obligation to attend this event. You are encouraged to invite family and friends.

Category: EventsTag: AI & disruption, Family wealth planning, Future-proofing your business, Market strategy

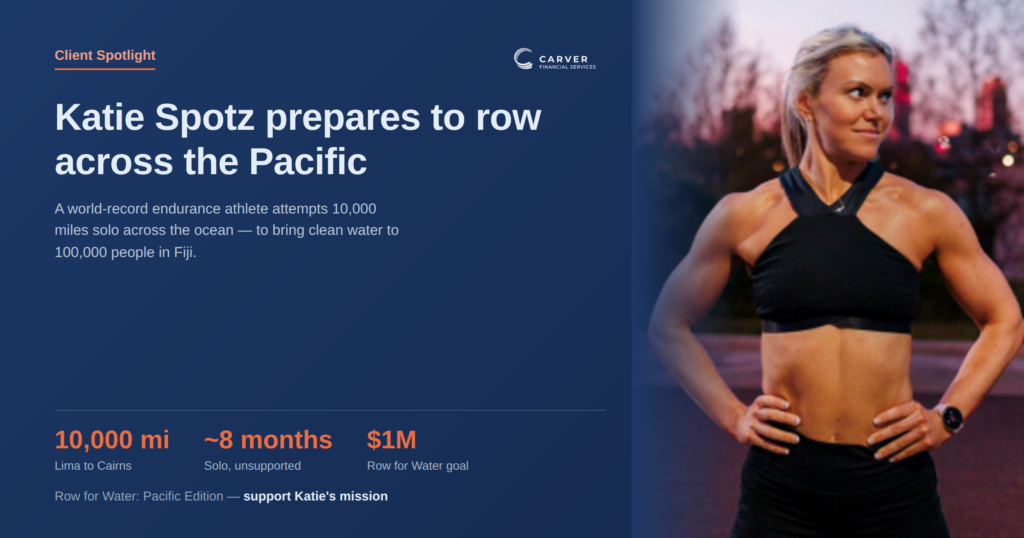
Katie Spotz Prepares to Row Across the Pacific — For a Cause Greater Than the Record Books

September 1, 2026 //  by Paige Courtot


This month, we’re proud to shine our Client Spotlight on Katie Spotz — niece of a valued Carver Financial Services client — whose extraordinary blend of athletic endurance and humanitarian purpose is about to carry her across one of the most daunting stretches of open water on Earth.

Katie is no stranger to pushing the limits of what’s physically possible. A world-record endurance athlete, author, speaker, U.S. Coast Guard veteran, and dedicated clean-water advocate, she has spent her career redefining what one person can accomplish — and who it can help along the way.

A History of Extraordinary Feats

Katie’s resume of accomplishments reads like a list of “impossible” tasks, checked off one by one:

  • Youngest person to row solo across the Atlantic Ocean
  • Swam the entire 325-mile length of the Allegheny River
  • Completed 11 ultramarathons in 11 consecutive days

But what sets Katie apart isn’t just the scale of these challenges — it’s the purpose behind them. Through her endurance feats, she has helped provide lasting access to clean water for more than 50,000 people around the world.

Her Boldest Challenge Yet

Now, Katie is preparing for the most ambitious undertaking of her career. During a launch window from late December 2026 to early January 2027, she will attempt a 10,000-mile solo row across the Pacific Ocean, traveling from Lima, Peru, to Cairns, Australia. She’ll spend approximately eight months alone at sea, without a support boat, relying entirely on her own strength, preparation, and resolve.

If successful, Katie will make history as:

  • The first woman to row solo from South America to Australia
  • The first American woman to row the Pacific Ocean solo
  • A record-setter for the longest nonstop solo ocean row by a woman

Rowing for a Reason

For Katie, this journey has never been about personal glory alone — it’s about the communities she can uplift along the way. Her Row for Water campaign aims to raise $1 million to bring clean-water access to 100,000 people in Fiji, continuing her long-standing mission of turning physical endurance into lasting global impact.

It’s a powerful reminder that resilience, when paired with purpose, can change lives far beyond the finish line.

How You Can Support Katie’s Mission

Katie’s journey across the Pacific will test her physically and mentally in ways few can imagine — but the reward, if she succeeds, extends far beyond personal achievement. It’s an opportunity to bring clean, safe drinking water to tens of thousands of people who need it most.

Donate here to support Katie’s Row for Water – Pacific Edition campaign

We’re honored to know Katie through our client community, and we’ll be following her journey closely as she prepares to set out on this historic row. Stay tuned for updates as her launch window approaches.

Category: Uncategorized

Wings & Wheels 2026

August 28, 2026 //  by Paige Courtot

Category: Video

September 2026

August 13, 2026 //  by Paige Courtot

Category: Client Memo

What Documents Do I Need to Keep on File?

August 13, 2026 //  by Paige Courtot

What Documents Do I Need to Keep on File?

Download the Guide

Most people have a filing cabinet, a desk drawer, or a digital folder stuffed with paperwork they’re afraid to throw away — and no real sense of what’s actually necessary to keep. The result is often one of two problems: important documents get shredded too soon, leaving a gap when they’re needed most, or nothing ever gets thrown away, turning recordkeeping into a permanent, disorganized burden.

The truth is that different documents need to be kept for different reasons and different lengths of time. Some protect you in the event of an audit. Some establish eligibility for benefits. Some simply prove that a debt has been paid or a deduction was legitimate. Knowing which is which can save you real time, stress, and risk down the road.

Here’s a breakdown of what to keep, and for how long, organized by category.

Legal Documents

Legal paperwork tends to fall into two buckets: documents you’ll need once and can then archive permanently, and documents tied to a specific life event that you’ll need to produce again later.

  • Citizenship and residency documents. If you’re a U.S. citizen, keep your Social Security card, birth certificate, and passport on file indefinitely. If you’re a foreign national, hold onto everything related to your entry into the U.S. — passport, Green Card, and I-94 — for the same reason.
  • Estate planning documents. Keep a copy of your Will, any Trusts, Powers of Attorney (both general and healthcare), your Living Will, and your beneficiary designations. Store the originals somewhere secure, and give copies to the people who play a role in carrying out your wishes — your agents, Executor(s), and Trustee(s). If something happens to you, the people who need these documents shouldn’t have to search for them.
  • Marriage records. If you’re currently married, keep your marriage certificate. It’s often required for a legal name change, proof of marriage for insurance benefits, or a joint mortgage application. If you signed a prenuptial agreement, store the original somewhere safe as well.
  • Divorce records. Divorce papers should be kept indefinitely. They can affect everything from asset division to future benefit eligibility.
  • Military discharge papers. If you served in the military, your discharge papers may be required to prove eligibility for veterans’ benefits, so they’re worth keeping permanently.
  • Safe deposit box documentation. If you have a safe deposit box, keep the relevant paperwork on file so that access isn’t a barrier for you or your heirs.

Tax Documents

Tax recordkeeping rules are some of the most specific — and most commonly misunderstood.

  • General rule: Keep at least three years of state and federal tax returns, along with supporting documentation such as W-2s, 1099s, and year-end statements from banks and investment accounts.
  • State-specific rules: Some states, including California, require you to keep tax returns for longer than three years. Check your state’s specific requirements.
  • Underreported income: If you believe you may have failed to report income equal to more than 25% of your gross income, keep six years of tax returns on file. This aligns with the IRS’s extended statute of limitations for substantial underreporting.
  • Worthless securities or bad debt: If you’re claiming a loss for worthless securities or a bad debt deduction, keep those records for seven years.
  • W-2s: Keep all your W-2s until you begin collecting Social Security, since they can be used to verify your earnings history.
  • Gifts and inheritances: If you’ve made taxable gifts or received an inheritance, keep every Form 709 you’ve filed, along with any Forms 8971 or 706 you’ve received, in your permanent records.

Healthcare Documents

Healthcare-related recordkeeping is often overlooked until it’s needed — usually at the worst possible time.

  • Medicaid planning. If there’s a chance you’ll apply for Medicaid, particularly to help cover long-term care costs, keep detailed financial statements and transaction records for the previous five years. Medicaid generally applies a five-year look-back period when reviewing applications, and gaps in your records can complicate or delay approval.
  • Health Savings Accounts (HSAs). Keep every medical receipt from the date your HSA was opened. These receipts may be needed to substantiate tax-free withdrawals, even years later.
  • Medical expense deductions. If you’ve written off medical expenses on your tax return, keep those records for as long as you keep your tax returns — generally three years.
  • Medicare. If you’re enrolled in Medicare, keep your Medicare Summary Notices for at least a year, or until any related bill is paid in full. If you’re enrolled in an employer drug plan considered “creditable,” keep the annual Notice of Creditable Coverage your employer provides — you’ll need it if you enroll in Part D later.

Asset and Debt Related Documents

This is often the largest and most complex category, especially for people who own investments, retirement accounts, real estate, or a business.

Investment and bank accounts

  • Keep your most current statements on file, whether paper or electronic.
  • Keep your end-of-year statement until you’ve completed your tax return for that year.
  • If you own investments purchased before 2012 — the year custodians were first required to track cost basis — keep records of what you paid for those non-covered investments. Your 1099 may not report cost basis on older holdings, so your own records may be the only proof you have.

Retirement accounts

  • Keep documentation of any contributions and withdrawals, including IRS Form 5498.
  • If you took a Coronavirus-Related Distribution, retain your withdrawal request and Form 1099-R.
  • If you completed a Roth conversion, keep records showing the conversion.
  • If you made non-deductible traditional IRA contributions, keep Form 8606 until the account has been fully withdrawn, since it’s used to track your cost basis over time.

Small business ownership If you own a business, keep the following as part of your permanent records:

  • Federal EIN, business formation documents, ownership agreements, and business licenses
  • Payroll records, employment tax records, and expense receipts
  • Business asset records, such as purchase and sales invoices, deeds, and titles
  • Records of employee benefits, including retirement plan documents

Debts If you have a mortgage, student loans, or other debt, keep the loan documents until the loan is paid off. Once it’s paid off, keep documentation proving the debt was satisfied in full — this can matter years later if a lender’s records are ever incomplete or disputed.

Property If you own real estate or automobiles, keep deeds, titles, settlement statements, and bills of sale until you decide to sell. Also keep documentation of any capitalized purchase-related fees, since they affect your cost basis.

Home office deductions If you’re self-employed and deduct home office expenses, keep receipts for housing and home office-related costs — utility bills, mortgage statements, and similar documentation — to support the deduction if it’s ever questioned.

Home improvements Keep receipts for home improvements. They can be used to substantiate adjustments to your property’s cost basis when you eventually sell.

Property in multiple states If you own real property in more than one state, keep detailed records — receipts, travel itineraries, and similar documentation — proving which state you lived in for the majority of the year. This is especially important if you’re concerned about state income tax liability or need to establish residency in a particular state.

Other Documents

  • Higher education records. Keep copies of diplomas, transcripts, or certifications proving you completed coursework — these can matter for professional licensing or employment verification well after graduation.
  • Insurance policies. Keep your most current homeowners, disability, and life insurance policies on file, and replace outdated versions as they renew.
  • Employment contracts. If you’re currently employed, keep any signed contracts on file, including non-solicit or non-compete agreements. These can become relevant if you change jobs or start a business later.

Why This Matters

Recordkeeping isn’t just an administrative chore — it’s a form of financial protection. The right documentation can be the difference between a smooth Medicaid application and a five-year scramble to reconstruct financial history. It can determine whether a tax deduction holds up under audit, or whether a family member can settle an estate without unnecessary delay.

At the same time, holding onto everything forever isn’t the goal either. A thoughtful approach — knowing what to keep, for how long, and why — makes it easier to stay organized without being buried in paperwork you’ll never need.

If you’re not sure whether your recordkeeping is where it should be, or if you have questions about how these guidelines apply to your specific situation, we’re happy to help you sort through it.


Any opinions are those of Randy Carver and not necessarily those of Raymond James. Expressions of opinion are as of this date and are subject to change without notice. Raymond James and its advisors do not offer tax or legal advice. You should discuss any tax or legal matters with the appropriate professional. Investing involves risk and you may incur a profit or loss regardless of strategy selected, including diversification and asset allocation. Prior to making an investment decision, please consult with your financial advisor about your individual situation.

Category: Carver University

10.22.26 39th Annual CPE Event

August 8, 2026 //  by Paige Courtot

This year’s program will feature an important OBBA legislative and planning update covering critical changes impacting clients in 2026 and 2027, along with presentations showcasing state-of-the-art technology and advanced AI-driven tools that can identify sophisticated planning opportunities in minutes instead of hours.

Category: Events

5 Important Legal Documents When Your Child Turns 18

July 14, 2026 //  by Paige Courtot

When a child turns 18, they become a legal adult. Parents no longer have automatic access to their medical, educational, or financial information, and they cannot make decisions on their behalf without permission. To help protect your child and prepare for emergencies, consider these five important legal documents:

FERPA Waiver

  • Allows parents to access college education records, including grades, tuition, financial aid, and disciplinary information.
  • Helpful if parents are assisting with college finances or want to stay informed.

HIPAA Waiver

  • Gives parents permission to access their adult child’s medical records and speak with healthcare providers.
  • Does not allow parents to make medical decisions.

Advance Directive (Medical Power of Attorney & Living Will)

  • Names someone to make healthcare decisions if the child is unable to do so.
  • Includes instructions for medical treatment and life-support preferences if the child becomes seriously ill or incapacitated.

Financial Power of Attorney

  • Authorizes a trusted person to manage financial matters if the child is unable to do so.
  • Can include paying bills, managing bank accounts, handling investments, filing taxes, or other financial responsibilities.
  • Authority can be broad or limited, depending on the document.

Simple Will

  • Specifies how the child’s assets should be distributed after death.
  • Helps avoid legal complications and allows an executor to manage both physical and digital assets, such as social media accounts.

Key Takeaway:

Having these documents in place helps ensure parents or another trusted individual can assist an adult child with education, healthcare, finances, and estate matters when needed. An estate planning attorney can help prepare the appropriate documents for your family’s situation.


Any opinions are those of Randy Carver and not necessarily those of Raymond James. Expressions of opinion are as of this date and are subject to change without notice. Raymond James and its advisors do not offer tax or legal advice. You should discuss any tax or legal matters with the appropriate professional. Investing involves risk and you may incur a profit or loss regardless of strategy selected, including diversification and asset allocation. Prior to making an investment decision, please consult with your financial advisor about your individual situation.

Category: Carver University

The 50/30/20 Budget Rule: A Simple Formula for Financial Success

June 30, 2026 //  by Paige Courtot

Managing your money doesn’t have to be complicated. With so many budgeting methods available, it’s easy to feel overwhelmed by spreadsheets, expense trackers, and financial jargon. Fortunately, the 50/30/20 budget rule offers a simple and effective way to take control of your finances without making budgeting feel like a full-time job.

Whether you’re just starting your financial journey or looking for an easier way to manage your income, the 50/30/20 method provides a practical framework that can help you build healthy financial habits.

What Is the 50/30/20 Budget Rule?

The 50/30/20 rule is a budgeting strategy that divides your after-tax income into three categories:

  • 50% for Needs
  • 30% for Wants
  • 20% for Savings and Debt Repayment

Instead of tracking every dollar you spend, this method focuses on maintaining the right balance between essential expenses, lifestyle choices, and your financial future.

50% for Needs

Needs are the essential expenses you must pay to maintain your daily life. These are costs you cannot easily avoid.

Examples include:

  • Rent or mortgage payments
  • Utilities
  • Groceries
  • Transportation
  • Health insurance
  • Minimum debt payments
  • Childcare
  • Basic phone and internet service

If your essential expenses exceed 50% of your income, you may need to look for ways to reduce costs, such as refinancing debt, finding less expensive housing, or cutting unnecessary services.

30% for Wants

Wants are the non-essential purchases that improve your quality of life but aren’t necessary for survival.

Examples include:

  • Dining out
  • Streaming subscriptions
  • Vacations
  • Entertainment
  • Shopping
  • Gym memberships
  • Hobbies
  • Premium cable or internet packages

Spending on wants isn’t a bad thing. In fact, allowing room for enjoyment can make your budget more sustainable over the long term. The key is avoiding lifestyle inflation that leaves little room for saving.

20% for Savings and Financial Goals

The final 20% should be dedicated to building your financial future.

This category may include:

  • Emergency fund contributions
  • Retirement savings
  • Investments
  • Extra payments toward loans
  • Saving for a home
  • College savings
  • Building other long-term financial goals

Many financial experts recommend building an emergency fund that covers three to six months of living expenses before focusing heavily on investing.

Example Budget

Suppose your monthly take-home pay is $4,000.

Following the 50/30/20 rule, your budget would look like this:

Category Percentage Monthly Amount
Needs 50% $2,000
Wants 30% $1,200
Savings & Debt 20% $800

This structure gives you a clear financial roadmap while keeping your spending balanced.

Benefits of the 50/30/20 Method

Easy to Follow

Unlike detailed budgeting systems that require tracking every purchase, the 50/30/20 rule is simple enough for almost anyone to implement.

Encourages Saving

By automatically allocating 20% of your income toward savings or debt reduction, you’re consistently working toward long-term financial security.

Flexible

Life changes, and so does your budget. The 50/30/20 method can be adjusted as your income increases or your financial priorities evolve.

Reduces Financial Stress

Having a clear spending plan helps eliminate uncertainty and gives you confidence that you’re making progress toward your goals.

Potential Drawbacks

While the 50/30/20 rule works well for many people, it isn’t perfect.

Some individuals living in high-cost areas may find that necessities consume far more than 50% of their income. Others with significant debt may need to devote more than 20% toward repayment.

Additionally, people with irregular income—such as freelancers or seasonal workers—may need a more flexible budgeting strategy that adjusts from month to month.

Tips for Making the Rule Work

  • Track your spending for one month before creating your budget.
  • Automate transfers to your savings account.
  • Review your budget every few months.
  • Increase your savings percentage whenever you receive a raise.
  • Avoid treating every expense as a “need.”
  • Build an emergency fund before making large discretionary purchases.

Is the 50/30/20 Rule Right for You?

The 50/30/20 budget rule is an excellent starting point for anyone looking to improve their financial health. Its simplicity makes it easy to understand, while its balanced approach encourages responsible spending without sacrificing enjoyment.

Remember that no budgeting system is one-size-fits-all. The percentages are guidelines, not strict rules. If your circumstances require adjustments, don’t hesitate to modify the allocation to better fit your financial goals.

Final Thoughts

Budgeting isn’t about restricting your life—it’s about giving every dollar a purpose. The 50/30/20 rule provides a straightforward framework that helps you cover your essential expenses, enjoy the present, and prepare for the future.

By consistently following this method and reviewing your finances regularly, you’ll be better positioned to reduce debt, grow your savings, and achieve long-term financial stability. Small, consistent financial decisions made today can lead to significant rewards in the years ahead.

Category: Carver University

A Guide to Building Credit

June 19, 2026 //  by Paige Courtot

Building credit may not seem important when you’re young, but establishing a strong credit history early can make a significant difference in your financial future. A good credit score can help you qualify for apartments, secure lower interest rates on loans, obtain credit cards with better rewards, and even improve your chances of getting certain jobs.

The good news is that building credit doesn’t require taking on large amounts of debt. With responsible habits and a little patience, young adults can create a solid financial foundation.

Why Credit Matters

Your credit score is a number that reflects how responsibly you’ve managed borrowed money. Lenders, landlords, and sometimes employers use this score to evaluate your financial reliability.

A strong credit score can help you:

  • Qualify for loans and credit cards
  • Receive lower interest rates
  • Rent an apartment more easily
  • Save money over time
  • Build financial independence

Because credit history takes time to develop, starting early gives you an advantage.

  1. Become an Authorized User

One of the easiest ways to begin building credit is by becoming an authorized user on a parent or guardian’s credit card account. If the primary cardholder has a history of on-time payments and low balances, that positive history may appear on your credit report.

However, this strategy only works if the primary account is managed responsibly. Late payments or high balances can negatively affect your credit as well.

  1. Open a Starter Credit Card

Many banks offer student credit cards or beginner credit cards designed for people with limited credit history. These cards often have lower credit limits and simpler approval requirements.

When using a starter credit card:

  • Make purchases you can afford
  • Pay the balance in full each month
  • Avoid carrying unnecessary debt
  • Never miss a payment

Consistent on-time payments are one of the most important factors in building good credit.

  1. Consider a Secured Credit Card

If you don’t qualify for a traditional credit card, a secured credit card can be an excellent alternative. With a secured card, you provide a refundable security deposit that serves as collateral.

Using a secured card responsibly can help establish credit history and may eventually allow you to upgrade to a traditional credit card.

  1. Pay Every Bill on Time

Payment history is the largest factor affecting your credit score. Even a single late payment can hurt your credit and remain on your credit report for years.

Set up automatic payments or reminders to ensure that bills are paid on time. This includes:

  • Credit card payments
  • Student loans
  • Auto loans
  • Utility bills that may be reported to credit bureaus

Developing a habit of paying on time is one of the smartest financial decisions you can make.

  1. Keep Credit Utilization Low

Credit utilization refers to the percentage of your available credit that you’re using. Experts generally recommend keeping utilization below 30%, and lower is often better.

For example, if your credit card limit is $1,000, try to keep your balance below $300.

Low utilization demonstrates responsible credit management and can help improve your credit score over time.

  1. Avoid Applying for Too Many Accounts

Each credit application can result in a hard inquiry on your credit report. Applying for several credit cards or loans within a short period may signal financial risk to lenders.

Only apply for credit when you genuinely need it and when you’re reasonably confident you’ll qualify.

  1. Monitor Your Credit Regularly

Reviewing your credit reports can help you track your progress and identify errors or fraudulent activity.

Regular monitoring allows you to:

  • Verify that accounts are being reported correctly
  • Spot unauthorized activity
  • Understand factors affecting your score
  • Measure your improvement over time

Building awareness of your credit profile is an important part of financial literacy.

Common Mistakes to Avoid

As you begin building credit, watch out for these common pitfalls:

  • Missing payment due dates
  • Maxing out credit cards
  • Applying for too many accounts
  • Ignoring credit reports
  • Borrowing more than you can afford to repay

Credit should be treated as a financial tool, not free money.

Final Thoughts

Building credit as a young person is less about borrowing large amounts of money and more about demonstrating consistent financial responsibility. By making payments on time, keeping balances low, and using credit carefully, you can establish a strong credit history that benefits you for years to come.

The earlier you start building healthy credit habits, the more opportunities you’ll have when it comes to renting an apartment, buying a car, purchasing a home, or achieving other financial goals. Small actions today can lead to significant financial advantages tomorrow.


Category: Carver University

  • Page 1
  • Page 2
  • Page 3
  • Interim pages omitted …
  • Page 34
  • Go to Next Page »

Footer

Let’s Get Started


We’re ready to help you achieve your vision. Contact our team today.

Contact us

OUR APPROACH
ABOUT US
RESOURCES
EXPERIENCES

CONTACT US

OUR OFFICES
7473 Center St.
Mentor, OH 44060
Phone: 440.974.0808
Toll-Free: 800.627.7279
Email: carverfinancialservices@ raymondjames.com

STAY IN TOUCH
         twitter   

RECOGNIZED BY


(Please click here for award criteria & disclosures.)

Securities offered through Raymond James Financial Services, Inc., member FINRA / SIPC. Investment advisory services offered through Raymond James Financial Services Advisors Inc. Carver Financial Services is not a registered broker/dealer and is independent of Raymond James Financial Services.

Raymond James financial advisors may only conduct business with residents of the states and/or jurisdictions for which they are properly registered. Therefore, a response to a request for information may be delayed. Please note that not all of the investments and services mentioned are available in every state. Investors outside of the United States are subject to securities and tax regulations within their applicable jurisdictions that are not addressed on this site. Contact your local Raymond James office for information and availability.

Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members.

Site Footer

Copyright© 2026 · Carver Financial Services · Our Privacy Policy · Member FINRA/SIPC · Legal Disclosures